What is a FICO® Score?
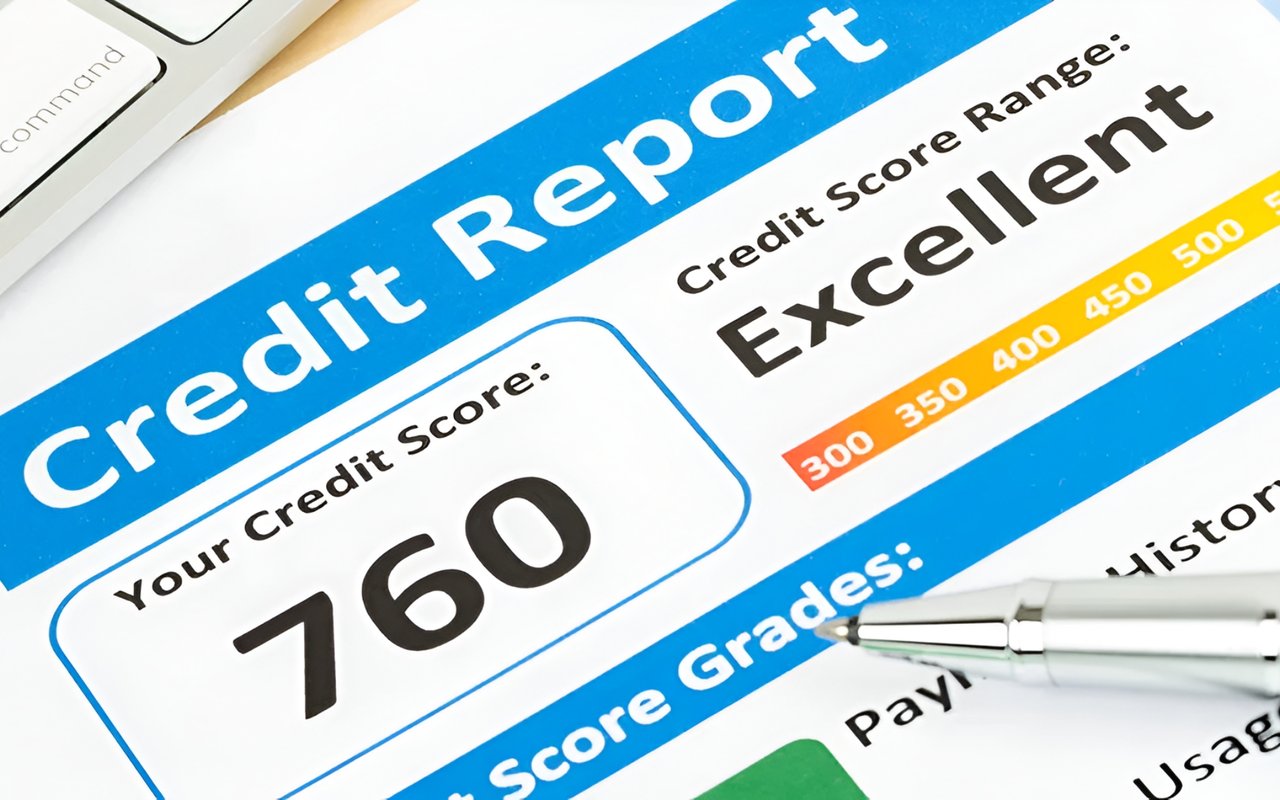
FICO® stands for Fair Isaac & Company and is the name of the most well-known credit scoring system, used by Experian. The credit bureau’s computer evaluates a complete credit profile and assigns a score, which is used to estimate creditworthiness. Each of the three bureaus (Experian, Trans Union, Equifax) employs its own scoring system, so a given person will usually have 3 separate scores. Someone with a higher score will be viewed as a better risk than someone with a lower score. Typically, scores will range from about 600 to 700 or above, although some cases will be outside this range.
What Kind of Score Do I Need for a Home Loan?
There are as many answers to this question as there are loan programs available. Most lenders will take the average of all 3 scores to evaluate an application. Niche loans, such as Easy Qualifier and low down payment loans, will have higher FICO® requirements.
How is My Score Determined?
The FICO® model has 5 main elements:
- Past payment history (about 35% of score). The fewer the late payments, the better. Recent late payments will have a much greater impact than a very old Bankruptcy with perfect credit.
Myth - paying off cards with recent late payments will fix things. Payoffs do not affect payment history. - Credit use (about 30% of the score). Low balances across several cards are better than the same balance concentrated on a few cards used closer to maximums. Too many cards can bring down the score, but closing accounts can often do more harm than good if the entire profile is not considered. Be careful when closing accounts!
- Length of credit history (15% of score). The longer accounts have been open, the better for the score. Opening new accounts and closing seasoned accounts can bring down a score a great deal.
- Types of credit used (10% of score). Finance company accounts score lower than bank or department store accounts.
- Inquiries (10% of score). Multiple inquiries can be a risk if several cards are applied for or other accounts are close to maxed out. Multiple mortgage or car inquiries within a 14-day period are counted as one inquiry.
How Can I Raise My Score
Your score can only be changed by the way that item is reported directly to the credit bureaus (Experian, TU, Equifax). Written confirmation from the creditor is required. It is best to make these corrections before you try to purchase a home, because you can never be sure of the exact impact a change will have on your score.
What Does This Mean to Me?
You should have your credit reviewed before you look for a home, and work with a professional loan officer to make sure your loan is based on the most accurate information.